Foreign Investors in the U.S.

Investing in the U.S.: Tax Strategy from Entry to Exit

We help foreign investors, families and companies determine in advance how the U.S. will tax an investment and the income connected with it: who should own the asset, when U.S. tax residency begins, which taxes, withholding and filings may apply, and what happens when the asset is sold, the structure changes, or the investor moves to the United States.
Our role is to connect the investment decision, ownership structure, real estate and other assets, annual compliance, estate tax and eventual exit into one clear tax plan.
Who this service is for

For Foreign Investors, Families and Companies with U.S. Tax Exposure

Tax planning is most valuable before a purchase, company formation, capital transfer or move — while the structure can still be chosen. We also step into existing investments when the tax treatment needs to be reviewed, missed filings need to be addressed, withholding needs to be assessed, or a future sale needs to be prepared.

U.S. Real Estate Investors

Investors buying apartments, homes, commercial properties or other U.S. real estate. We connect the ownership structure, rental taxation, depreciation and cost segregation, sale withholding, estate tax and the eventual exit from the investment within one tax model.
Private Investors in the U.S.

Individuals placing capital into U.S. real estate, businesses or investment assets, or planning a family move, children’s education, retirement or a gradual change of tax residency. Before U.S. tax status changes, we review and optimize the profile and treatment of foreign assets and structures that may become subject to U.S. taxation and additional reporting after the move.
Foreign Business Owners

Owners forming a U.S. company, operating in the U.S. through a foreign company, selling goods or services to U.S. customers, or using online marketplaces. To optimize the U.S. tax position, the source of income, whether the activity rises to a U.S. trade or business, treaty protection, required withholding and reporting must be analyzed separately.
Owners of U.S. Assets

Investors who already own a U.S. company, real estate, stock, partnership interest, digital assets or U.S.-source income and want to confirm that the existing structure remains appropriate for their tax status, objectives and reporting obligations. Where necessary, we separately address missed returns and available ways to correct the position while minimizing penalties.

CLIENT PROBLEMS

Why International Tax Planning?

The same asset or income can be taxed very differently depending on the investor’s tax status, the source and character of the income, the ownership structure, the applicable tax treaty and what happens next. We plan these decision points in advance — before a choice becomes difficult or expensive to change.
Tax Status Changes the Entire Analysis
Immigration status and tax residency are not the same. A green card, the number of days spent in the U.S., available exceptions, treaty provisions and the residency start date can change what income and assets enter the U.S. tax system. Travel dates and visa type are therefore part of the tax strategy, not a formality.
A U.S. Company Is a Tool, Not a Complete Tax Strategy
A U.S. company can often support tax planning, but the result depends on the entity type, the number and status of owners, the chosen tax classification and related-party transactions. For example, a U.S. company with one foreign owner may have mandatory annual reporting even when it has no income and no tax due. Failure to file Form 5472 can trigger a $25,000 penalty for each year.
U.S. Real Estate Has a Tax Life Cycle from Purchase to Sale
Ownership structure, rental taxation, expenses, depreciation and cost segregation, financing, withholding on sale and estate tax need to be considered in advance — and they are interconnected. For a nonresident, the choice between tax on gross rental income and taxation of net income after expenses can be especially important. This chain is best planned as one project — before purchase or during ownership, but before sale.
Multiple Advisers Need One Coordinator
In a U.S. investment, the broker, lawyer, bank, property manager and tax-return preparer are responsible for different parts of the transaction. We coordinate their work around one U.S. tax position, one set of supporting documents and one action calendar.

HOW WE HELP

A Tax Strategy for the Full Life Cycle of the Investment

We begin with the client’s objectives and facts, then determine tax status, ownership structure, sequence of actions, required documentation and annual obligations. Tax planning should come before the transaction: once documents are signed, capital is transferred or residency changes, the available options usually narrow sharply.

Before Investing in the U.S.

Many tax consequences are determined by decisions made before money is transferred, an asset is purchased or the investor moves. We identify current and expected tax residency, expected types of income, ownership structure, treaty opportunities, potential federal estate tax, withholding, reporting obligations and the exit plan. For clients preparing to move to the U.S., we separately review foreign companies, funds, accounts and other assets because a change in status may bring worldwide income into the U.S. tax system and trigger complex additional reporting. The result is a written action map while changes can still be made.

Learn More

Buying U.S. Real Estate

A tax mistake is often built into a real estate transaction before closing: an unsuitable ownership structure, the wrong rental-income treatment or no exit plan can increase tax and complicate a later sale. We compare ownership options, rental taxation, expenses, depreciation and cost segregation, financing, annual compliance, sale withholding and estate tax. We prepare a document list and action calendar from purchase through future sale. If the property is already owned and returns were filed late or not filed at all, we separately review whether deductions can be preserved and the intended tax treatment restored.

Learn More

U.S. Company with a Foreign Owner

Forming a U.S. company does not by itself resolve the tax issues. A foreign owner may have mandatory reporting even when the company has no income and no tax due. We determine the preferred tax classification, the foreign owner’s obligations, treatment of related-party transactions, withholding and required filings. For a U.S. company with a single foreign owner, we separately review Form 5472 together with the pro forma Form 1120; filing can be triggered by owner contributions, distributions, loans or other related-party transactions. We establish an annual data-collection process so the company remains compliant after formation, not only on the day it is created.

Learn More

Moving to the U.S.

Moving to the United States can sharply change a family’s tax position: income and assets previously outside the U.S. tax system may become taxable or reportable once status changes. We model the transition from nonresident to U.S. tax resident, including green-card status, days of presence, the residency start date, possible exceptions and tax-treaty positions. We separately check whether residency arises in a particular state because state rules may differ from federal rules. Before the move, we review foreign companies, funds, accounts, trusts, gifts and other assets. This analysis is also important before selling appreciated assets, changing ownership structures or receiving large distributions.

Learn More

Selling U.S. Real Estate

When foreign owners sell U.S. real estate, they may face mandatory withholding of 15% of the transaction price even though the actual tax on the gain may be much lower. Before closing, we calculate the expected tax and withholding, assess whether a withholding certificate may reduce the amount, confirm tax identification numbers and model the effect of prior depreciation. After the sale, we prepare the tax calculation and, where withholding exceeds the actual tax, arrange the refund claim.

Learn More

U.S. Estate Tax

A foreign investor should consider U.S. estate tax before the U.S. asset is acquired, when changing the ownership structure is generally easier and less costly. We determine which assets are treated as U.S.-situs property for federal estate-tax purposes, whether estate-tax domicile differs from income-tax residency, whether a treaty applies and whether Form 706-NA may be required. For U.S. real estate and shares of U.S. corporations, this analysis is particularly important before acquisition. When needed, we coordinate specialized legal counsel, valuation professionals and advisers in the client’s home country.

Learn More

Foreign Company Doing Business in the U.S.

A foreign company can incur U.S. tax obligations even without forming a separate U.S. entity. The location of services, employees and agents, inventory, online marketplaces and other factual U.S. connections all matter. We analyze sales, services, employees, contractors, inventory, marketplaces and payment flows. We determine whether the company is engaged in a U.S. trade or business, what income is effectively connected with that activity, whether treaty protection through a permanent-establishment standard is available, and whether Form 1120-F is required. Where U.S. business activity is uncertain, we may recommend a protective return to preserve deductions and other tax benefits if the IRS later takes a different view. We also review transfer pricing, state taxes and sales tax.

Learn More

Individual Taxpayer Identification Number

Without an individual taxpayer identification number, a foreign investor may face delays in filing a return, receiving a refund or completing a transaction, while incorrect documentation of the income recipient’s status can lead to excess withholding. We determine whether an ITIN is needed, prepare Form W-7 and, when appropriate, coordinate identity verification through an IRS-authorized acceptance agent. We review Forms W-8 and Form 1042-S so that recipient status, type of income, treaty rate and actual withholding are consistent with one another.

Learn More

WHY US?

Tax Planning First. Then Structure, Documentation and Compliance.

A U.S. company, a tax return, foreign-status documentation or a technical analysis are tools. Our role is to determine what a particular investor actually needs, in what sequence the steps should be taken, and how tax decisions can be balanced with the investment itself.
  • One Accountable Coordinator

    The challenge in an international project is that the lawyer, bank, broker, property manager and tax-return preparer each see only their part of the transaction. We connect their work to one U.S. tax position, one set of documents and one sequence of actions. The client receives one tax plan and a clear allocation of responsibilities among the professionals involved.

  • From Investment Decision to Practical Implementation

    Even the best tax idea produces no result if it remains on paper and is not reflected in documents, payments, agreements and subsequent reporting. We build the sequence of actions, document checklist, withholding instructions, compliance calendar and assignments for the professionals involved, and then verify that the selected position has been implemented and properly reflected in subsequent filings.

  • Documentation Built Alongside the Strategy

    A common weakness in international projects is not the tax position itself, but the absence of documents proving that the actual activities match the plan. International matters may require evidence of tax status, beneficial ownership, treaty entitlement, the source and character of income, related-party transactions, tax basis and investment documentation. We build the supporting file together with the tax plan rather than after a request from a bank or the IRS.

  • Personal Involvement of the Founder

    Oleg Shmal is an international tax professional admitted to represent taxpayers before the Internal Revenue Service. He is personally involved in every international project; his professional background includes international taxation, work with leading global audit and advisory firms, and tax controversy matters in several countries.

“I approach every international project as one integrated tax story for the client, not as a collection of separate forms. We identify tax-efficient options for moving capital and, once the Client selects the strategy, help coordinate the required professionals and support implementation — from structure and withholding through annual compliance and, when needed, exit from the investment.”
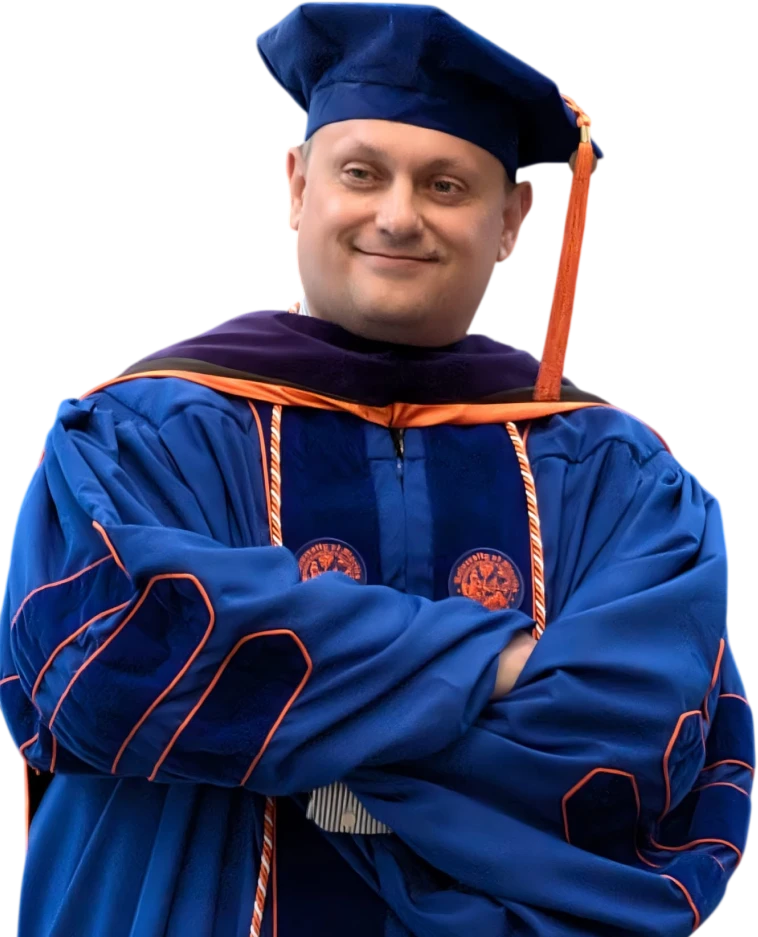
Oleg Shmal
Founder & Managing Director · Enrolled to Represent Taxpayers Before the IRS

SERVICE LEVELS

How much could it cost?

Fees depend on the number of countries, owners, companies and assets; the complexity of the tax-residency and treaty analysis; the volume of related-party transactions; and the state of the supporting documentation. Preparation and signing of tax returns, legal documents, valuations and outside professional services are billed separately unless expressly included in the engagement.
BLACK

Turn-key Implementation

$12,000
+ tax returns and outside professionals billed separately
For investors and families who need one integrated tax plan and coordination of implementation — from the ownership structure and withholding through transition into annual compliance.
  • Full U.S. entry diagnostic
  • Written tax strategy
  • Comparison of ownership structures
  • Real estate: sale withholding and estate tax
  • Withholding and annual compliance plan
  • Coordination with lawyers and advisers in the client’s home country
  • Implementation support and transition to annual service
Schedule Consultation
Gold

Consulting Support

$6,500
+ tax returns and outside professionals billed separately
For clients who need a written tax plan, comparison of the key alternatives and support implementing the most important steps, but not full project management.
  • Analysis of tax status and investment profile
  • Written tax plan
  • Ownership structure and compliance map
  • Real estate: withholding and preliminary estate-tax review
  • Implementation plan
  • Two implementation consultations
  • Instructions for the accountant, lawyer or other professional
Schedule Consultation
Silver

Diagnostic Review

$2,500
one-off
For professional investors who need to identify the main tax decision points, risk areas and mandatory reporting before a transaction, or review an existing structure.
  • Tax status and residency
  • Review of main categories of U.S.-source income and withholding
  • Principal ownership-structure alternatives
  • Preliminary estate-tax review
  • High-level review of the applicable tax treaty
  • Mandatory compliance map
  • Final consultation and next steps
Schedule Consultation

CASE EXAMPLES & TAX PLANNING NOTES

Where Tax Classification Changes the Economics of an Investment

Illustrative examples only. The tax result depends on the specific facts, investor status, documentation and the applicable tax treaty.
Rental Income: 30% of Gross Income or Tax on Net Profit
Rental income of a nonresident from U.S. real estate is generally subject by default to 30% tax on the gross amount without deduction of expenses. Where the requirements are met, an election may allow related expenses and depreciation to be taken into account, with tax calculated on net income at the applicable rates. Timing of the first return matters: a significant filing delay can put deductions at risk, although relief may be available in certain cases. The rental tax regime, ownership structure and method of tracking expenses should therefore be modeled before purchase.
Example of a tax election, not individualized tax advice.
Withholding on a Real Estate Sale Is Not the Final Tax
When U.S. real estate is sold by a foreign owner, the buyer is generally required to withhold 15% of the amount realized. This is an advance payment, not the final tax on the gain. Before sale, the actual expected tax can be estimated, tax identification numbers prepared, a potential reduction in withholding reviewed, and basis and depreciation documentation assembled. After closing, withholding is reconciled with the actual tax; if too much was withheld, the excess may be claimed as a refund.
Rules and exceptions depend on the transaction structure and the seller’s status.

Blog/Video Insights

Latest Insights

U.S. Tax Planning for International Founders Moving to Florida

1 min read · Oleg Shmal · September 2026

Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. tax system.Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. […]

Keep Reading
Disclaimer
The taxation of international investments depends on tax residency, domicile for estate-tax purposes, the investor’s country, the source and character of income, treaty entitlement, ownership structure, beneficial ownership, supporting documentation, applicable state law and the actual implementation of the transaction. The forms and tax treatments described above do not apply in every situation. Legal, immigration, trust and estate advice, valuations, foreign tax opinions, and preparation and signing of tax returns are provided or coordinated separately where applicable.
Miami Tax & Tech does not guarantee a particular amount of tax savings, refund or reduction in withholding and cannot guarantee that the Internal Revenue Service will accept any particular tax position.