ACCELERATED DEPRECIATION

Cost Segregation: Save Income Tax Via Buying Real Estate

We help current and prospective U.S. real estate owners implement cost segregation as part of a broader income-tax optimization strategy.

Anyone with active income above $200k who has exhausted standard planning tools should evaluate this approach.
Who this service is for

For Real Estate Owners and Those Who Need Advanced Tax Planning

Cost segregation is most valuable when combined with active business — use in your own business, professional rental activity, or platform-based short-term rental.

Real estate professionals

Those working with real estate as a primary occupation — including active investors, landlords, and developers with qualifying activity levels.

We help you maximize accelerated depreciation to offset active business income, ensuring your real estate portfolio works as hard for your tax strategy as it does for your bottom line.
High-Net-Worth Individuals

Who exhausted standard tax planning instruments and ready to engage in short-term rental.
Family Business Owners

For those who already own real estate or are ready to invest in it as part of a strategy to reduce taxes on income from their primary business.
International Investors

Foreign investors in U.S. real estate who need the most tax-efficient structure possible.

CLIENT PROBLEMS

Why Cost Segregation?

Cost segregation provides flexibility to accelerate tax deductions, use them against active income rather than rental income alone, and properly document the position for the IRS.
Inflation Erodes Depreciation
Depreciation 30 years from now is worth almost nothing because of inflation.
High Income Needs a Scalable Tax Tool
At $300,000+ of income, traditional tax-planning tools often have limited impact. Cost segregation can be different — and, importantly, it is scalable.
Real Estate Losses Can Get Trapped
Rental losses generally offset only passive income. Proper short-term rental structuring may allow those losses to offset active income, making the strategy useful well beyond real estate professionals.
Real Estate Offers Flexibility and Peace of Mind
Unlike some tax-planning instruments that may feel exotic or difficult to understand and manage, real estate remains a familiar and flexible asset: it can be managed and rented remotely, refinanced, sold, or held for the long term.

HOW WE HELP

Enhance Tax Planning Through Cost Segregation

Illustrative examples only. Tax treatment depends on the taxpayer’s facts and documentation.

Clinic Owner Investing in Short-Term Rentals

A clinic owner earns $500,000 from her business and acquires real estate for short-term rental. After cost segregation, the property may generate substantial tax losses during the first years of this new business activity. We analyze whether the rental qualifies as short-term, document the owner’s participation, and coordinate cost segregation so that accelerated depreciation deductions may offset active income from the clinic when the applicable requirements are met.

Learn More

IT Professional Using Real Estate to Reduce Tax Pressure

An IT professional earns $600,000 and wants to build a tax-efficient real estate portfolio while reducing taxes on income from the IT business. We help design a multi-year acquisition and short-term rental strategy, aligned with cost segregation estimates and documentation requirements, so that qualifying accelerated depreciation deductions may offset active IT business income as the portfolio grows.

Learn More

Foreign Investor Buying Miami Apartments

A foreign investor acquires a Miami apartment building with a $4.5 million depreciable basis. In one potential scenario, cost segregation allocates 17% of the cost to 5-year property and 8% to 15-year property. Combined with the accelerated depreciation provisions under the OBBBA, this could free up to $900,000 of capital sooner for another acquisition in the following year — which, in turn, may generate additional accelerated deductions.

Learn More

Car Wash Acquired Years Ago — the Tax Opportunity May Still Be There

The owner acquired a car wash with a $750,000 depreciable basis in 2010 without a cost segregation study. In an illustrative 2027 scenario, a study could identify approximately $405,000 of additional depreciation deductions, potentially generating about $150,000 in federal tax savings at a 37% rate. The accumulated depreciation adjustment may be recognized currently through an accounting method change — without amending each prior-year tax return.

Learn More

WHY US?

Tax planning first. Cost segregation as the instrument.

A cost segregation report can identify accelerated depreciation. Our role is to place that result into a client-specific tax strategy, implementation plan, and defense file.
  • Tax planning is the center

    We specialize in tax planning. Where a study is justified, we keep the tax result, timing, documentation, and implementation strategy at the center of the project.

  • From report to tax result

    We do not stop at a paper report. We help translate the study into projected deductions, return filing, preparer handoff, and practical implementation steps.

  • Documentation-led planning

    As a team with tax controversy background, we heavily aim to avoid going into the IRS dispute funnel. For this, we concentrate on meeting IRS criteria with convincing evidence.

  • Founder involvement

    Oleg Shmal, a tax professional licensed by the U.S. Department of the Treasury and authorized to represent taxpayers in disputes with the IRS, as well as an Associate Member of the American Society of Cost Segregation Professionals (ASCSP), is involved in every project.

“Every cost segregation project is personally reviewed by me. We coordinate with qualified engineers, build the documentation supporting the tax position, and take responsibility for the tax strategy and its implementation — from the technical study through the actual realization of the tax benefit: your money.”
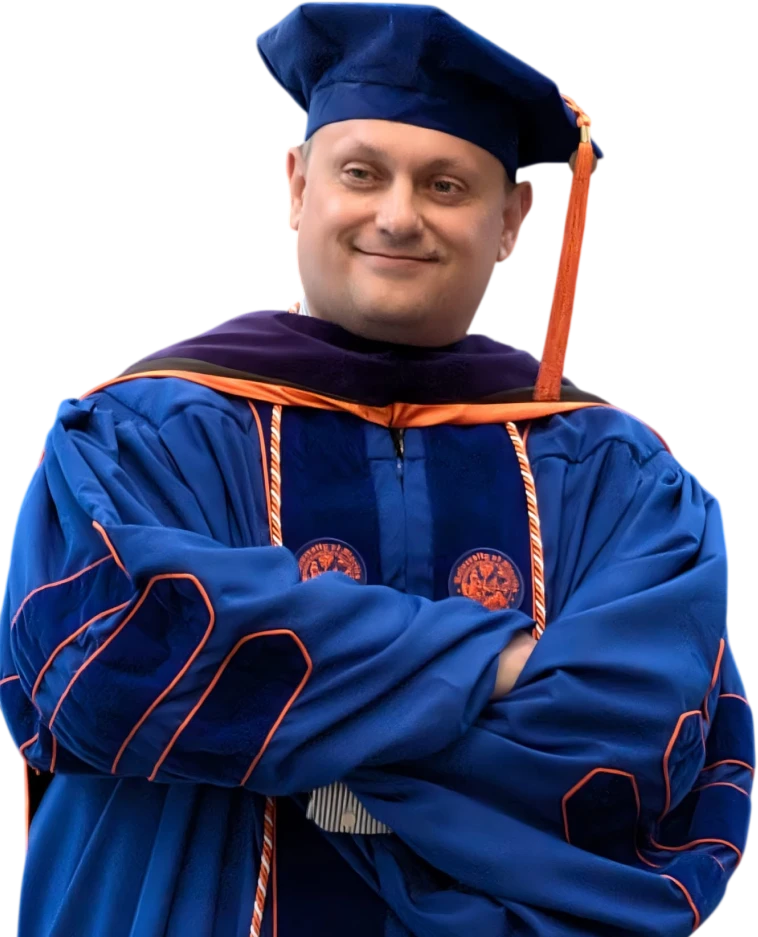
Oleg Shmal
Founder & Managing Director · EA License #00163210-EA · ASCSP Associate Member #A029-26

SERVICE LEVELS

How much could it cost?

Study fees are quoted separately. For properties below $1.5M, third-party they may be around $1.5k for residential and $2.5k for commercial properties.
Black


Turn-key Implementation

$6,000
+ 20% of 1st year tax savings + study fee
For clients who want cost segregation fully implemented as part of their broader tax strategy.
  • Full study coordination
  • Tax strategy development
  • Hands-on implementation
  • Bi-weekly calls
  • Tax-preparer/accountant coordination
  • Documentation support
  • Tax audit support coordination
Schedule Consultation
Gold

Consulting Support

$4,000
+$500 quarterly + study fee
For clients who need study coordination and professional support with implementation.
  • Study coordination
  • Tax strategy summary
  • Implementation plan
  • Quarterly advisory calls
  • Tax-preparer/accountant instructions
  • One-off documentation review
  • Initial tax audit support
Schedule Consultation
Silver

Diagnostic Review

$2,000
(one-off) + study fee
For real estate professionals who handle tax planning and implementation themselves.
  • Study data request
  • Clarification consultation
  • Study specialist introduction
  • High-level implementation plan
Schedule Consultation

ESTIMATE CALCULATOR

How much could you save?

Estimate your planning opportunities Answer a few quick questions to get a rough sense of your potential tax planning upside. This is illustrative only — not a tax or legal opinion.

Property Details

Property Purchase Details

Tax Details

Contact us to Discuss
Your Estimated Opportunity

Enter Your Property Details

Complete the form to estimate the potential depreciation benefit and federal tax savings.

CASE EXAMPLES & TAX PLANNING NOTES

Where Cost Segregation Can Create More Opportunity

Cost segregation is not only a way to accelerate deductions. It is also important to determine when to use those deductions and which properties can produce the strongest overall tax result.
The largest deduction today is not always the best result
Recent legislative changes can allow qualifying components to generate a very large deduction in the first year. But if that deduction creates a loss the client cannot use efficiently right away, taking the maximum amount today may not produce the best outcome. We evaluate not only the size of the potential deduction, but also the timing of its use — matching depreciation with the income of related taxpayers across multiple tax years in our automated tax modeling system, together with other limitations and the client’s broader tax strategy.
The optimal result depends on income levels, loss limitations, and tax elections.
Used real estate may also qualify for 100% accelerated depreciation
Under recent legislation, a building does not necessarily have to be new for 100% accelerated depreciation to apply. If the applicable requirements are met, qualifying components of previously used real estate acquired by a new owner may also be eligible for a full first-year deduction. This can be particularly relevant when acquiring existing apartment buildings, hotels, commercial properties, and other income-producing real estate. A significant tax benefit may arise even when the property itself was built many years ago. That potential benefit can also affect the economics of the transaction for both buyer and seller.
Eligibility depends on acquisition and placed-in-service dates, prior use, the relationship between the parties, and other applicable requirements.

Blog/Video Insights

Latest Insights

U.S. Tax Planning for International Founders Moving to Florida

1 min read · Oleg Shmal · September 2026

Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. tax system.Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. […]

Keep Reading
Disclaimer
Cost segregation depends on property-specific facts, documentation, taxpayer-level limitations, current tax law, state conformity, and proper implementation. Engineering reports, legal advice, valuations, and tax return preparation and signing are provided or coordinated separately where applicable.
Miami Tax & Tech does not guarantee tax savings, refunds, or IRS acceptance.