TAX PLANNING

Tax Planning: Structure Your Activities to Legally Pay the Lowest Taxes Reasonably Available

Tax planning is not about looking for deductions after income has already been earned. We structure business activities, investments, and transactions in advance so that tax is built into the economic model from the beginning and the client keeps more of what they earn.

That may mean changing an existing structure, but it can also mean starting a new activity when it has an independent economic purpose and produces a lawful tax result: a new company, a real estate investment, or a retirement program. We calculate the alternatives, help select the right combination, and carry it through implementation and into the client's account.
Who this service is for

For People Who Earn Enough for Tax Planning to Become a Separate Source of Economic Value

The higher the income and the more complex the asset structure, the more expensive the passive approach of ‘earn first, calculate the tax later’ becomes. We work with clients for whom it makes economic sense to change business structure, the way income is earned, investments, and the timing of actions in advance – and sometimes to create a new line of activity that has its own economic purpose and a meaningful tax effect.

Business Owners and Family Businesses

For owners of profitable companies who want the most tax-efficient combination of business and personal income. We analyze business form, owner compensation, salary, expense reimbursements, retirement programs, related companies, family-member participation, and investments outside the core business.
High-Income Professionals and Families

For physicians, IT professionals, executives, attorneys, and other clients with high active income for whom standard deductions are no longer enough. We look for solutions that can materially change the tax result: an additional business, real estate, retirement tools, investment projects, and the right timing of income and expenses across tax years.
Investors and Future Investors

For those who already own real estate, securities, or other assets – or are ready to begin investing for returns while also considering the tax effect. Before the asset is acquired, we evaluate ownership structure, the character of the activity, financing, depreciation, use of losses, and the eventual exit.
Affluent Clients Before a New Activity or Major Decision

For clients who are about to make a major change and have something meaningful at stake – launch a new business line, buy an asset, sell a company, change an ownership structure, receive a large payout, or relocate. The greatest number of lawful tax-planning options usually exists before the action is taken. We analyze them before the tax result becomes fixed.

CLIENT PROBLEMS

Why Tax Planning?

A tax return records the past. Tax planning changes the future: it allows activities, investments, and transactions to be structured in advance so that the client pays the lowest tax reasonably available under the law. In many cases, the strongest result does not come from another deduction inside the existing business, but from creating a new economically justified activity that can generate income, build an asset, and create tax deductions at the same time.
High Income Requires a New Tax Architecture
At income levels of several hundred thousand dollars, standard deductions often reach the ceilings intentionally built into the tax law and have only a limited additional effect. A material result usually requires larger decisions involving business structure, investments, real estate, retirement planning, a new line of activity, or a coordinated combination of several tools.
The Tax Result Is Created Before the Income or Transaction Occurs
After a bonus is paid, a transaction closes, or the year ends, many options disappear – because a completed transaction usually has only one, or at most a few, plausible tax treatments. The key tax decisions are made earlier: what activity to conduct, through which structure, when to invest, how to finance a purchase, when to recognize income, and which steps must be completed before the relevant deadline.
A Good Investment Can Generate Income, Build Capital, and Create a Tax Benefit at the Same Time
For example, a client with high active income may consider short-term rental activity not only as a real estate investment, but also as a separate business activity. If the applicable rental and participation requirements are met, tax losses increased by depreciation may, in some circumstances, reduce other active income.
Savings Exist Only After the Strategy Is Actually Implemented
A tax idea without timely action and documentation has no value. Elections, formation of a new company, participation in an activity, retirement contributions, contracts, accounting entries, and tax reporting must support the same economic model on which the calculation was based. And the tax authorities should be comfortable with the model suggested.

HOW WE HELP

We Build the Tax Strategy Around the Client’s Entire Economic Life

We begin with how the family earns money and where it allocates capital: businesses, spouses’ salaries, investments, real estate, retirement plans, and future transactions. We then model these elements as an interconnected system and look not for the single largest deduction, but for the combination of actions that produces the strongest overall result after taxes and implementation costs

Integrated Tax Plan for the Entire Family and Related Businesses

We calculate tax across the client’s entire connected structure: spouses, companies, salary, investments, real estate, and planned transactions are combined in one model. We test different combinations of actions and show the aggregate tax result in dollars, including how one strategy changes the effect of another.

We use modern automated tax-modeling systems for these calculations. The client receives a specific plan: what to do, in what sequence, how to implement the selected decisions, and what overall tax result they are expected to produce.

Learn More

Business Structure and Owner Compensation

We test whether the owner is losing money because of an unsuitable business form or an unstructured way of taking cash out of the business. We compare LLC, S corporation, and other applicable structures, reasonable compensation, distributions, expense reimbursements, retirement contributions, and transactions within the family and business. The objective is the best overall economics after tax and the cost of making the changes.

Learn More

The S Corporation as Part of a System, Not a Stand-Alone Technique

An S corporation can reduce taxes on earned income, but only when the economics work. We model profit, reasonable compensation, distributions, retirement contributions, expense reimbursements, and administrative cost. If the savings do not justify the complexity, we say so; if they do, we provide an implementation plan covering payroll, available deductions, and reporting.

Learn More

Strategies for High Active Income

When salary, bonuses, or business profits are already high, we look beyond standard deductions. That can include a new business activity, investment activity, real estate, retirement solutions, and other strategies that change not only the return, but the way income is earned and capital is accumulated.

Learn More

Real Estate as Part of the Tax Strategy

For a conservative high-income client, real estate can be more than a passive investment. We model long-term and short-term rental activity, owner participation, financing, depreciation, and the use of potential losses. Subject to the applicable rules, there may be ways to reduce tax on current active income through an asset class as familiar and tangible as real estate.

Learn More

Retirement Programs as a Way to Move Part of Profit Into Capital

For a profitable business, a standard retirement plan may not be enough. We model available designs based on the owner’s age, income, and employee population to determine how much profit can be directed into retirement arrangements rather than current tax. When appropriate, we coordinate the calculation and implementation with the plan administrator.

Learn More

Planning a Major Transaction Before the Documents Are Signed

The sale of a business, real estate, or an ownership interest can create a six-figure tax liability in a single day. Before signing, we model deal structure, purchase-price allocation, timing of income recognition, available losses and deductions, possible installment treatment, and related decisions. After closing, most of these opportunities are no longer available.

Learn More

Implementation and Result Control

We do not end the engagement with a presentation of our report. Once the client selects a strategy, we build an action calendar, prepare the required documentation, and assign implementation steps to the accountant, payroll provider, retirement-plan administrator, attorney, and other participants. Before the return is filed, we check that the economic activity, documentation, and accounting align with the assumptions used in the tax model. We are also prepared to advise the client if an IRS inquiry or dispute arises, although our objective is to reduce that risk through proper planning from the outset.

Learn More

WHY US?

We Do Not Plan the Tax Return – We Plan the Activity That Creates the Tax Result

Our work begins where routine tax compliance ends. We do not wait until year-end to calculate tax on actions that have already occurred. We help the client change the economic model in advance – launch a new business line, restructure compensation, acquire an asset, redesign a transaction, or implement another scenario – and then carry the selected strategy through documentation, accounting, and the tax return.
  • We Calculate the Combined Result Rather Than Adding Up Separate Deductions

    Tax strategies interact. A new deduction can change the marginal rate, the use of losses, the amount of other deductions, or the tax of another family member. We therefore model the entire connected structure at the same time and compare the total tax under different combinations of decisions.
    The client sees not ‘the savings from each idea,’ but how much the family as a whole will pay in federal tax, state tax, and payroll taxes – and how much remains after implementation costs.

  • We Are Not Limited to What the Client Does Today

    If the strongest tax result requires a new economically justified activity, we consider it alongside changes to the existing business. For example, a client with high active income may acquire property for short-term rental and, if the relevant requirements are met, use accelerated depreciation and resulting tax losses as part of the broader tax strategy.

  • We Build the Tax Position to Reduce the Risk of a Future Dispute

    We determine in advance which facts, calculations, and documents should support the selected strategy. Our objective is not to argue with the IRS after the fact, but to reduce the likelihood of a dispute through a properly structured position, real economic activity, and documentation from the outset. If a dispute nevertheless arises, our team is prepared for it.

  • Founder involvement

    Oleg Shmal is a federally authorized tax practitioner with more than 25 years of experience in tax planning and tax controversy, including senior leadership roles at international professional-services firms. He is personally involved in defining the engagement, selecting material strategies, and discussing critical planning, implementation, or controversy issues with the client.

“Tax planning should safely make the client money. If a strategy does not leave the client with more money after taxes, expenses, and implementation costs – or creates an unacceptable risk of a tax dispute – the strategy is not worth pursuing. That is why we start not with the return and not with a deduction, but with a different question: what activity can be built or changed to produce a better economic result while legally paying less tax?”
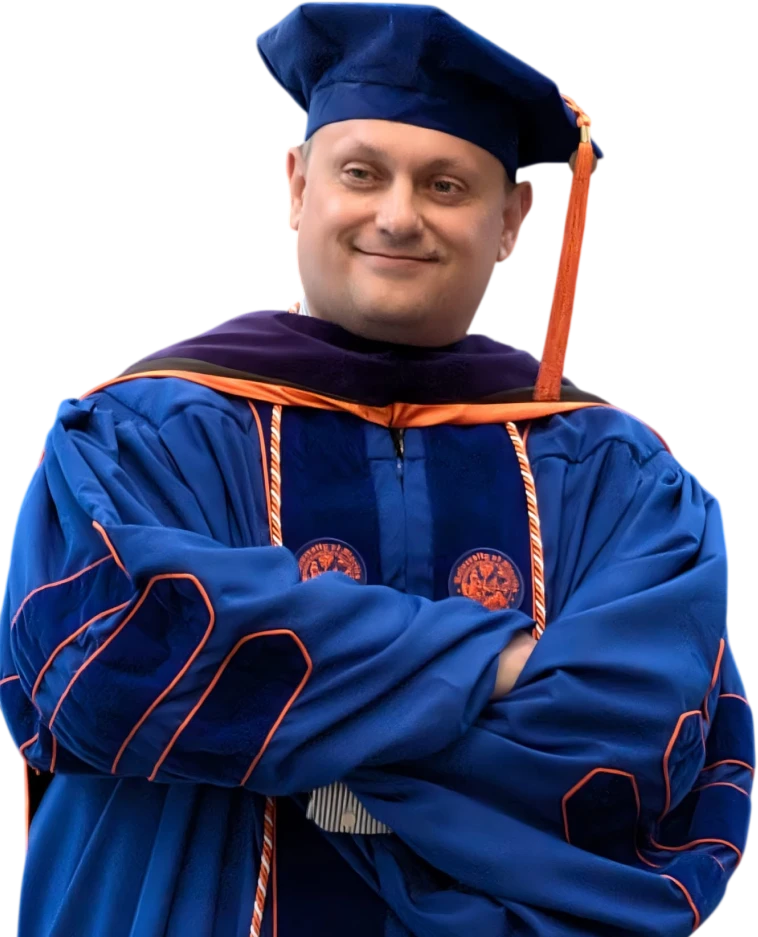
Oleg Shmal
Founder u0026 Managing Director · EA License #00163210-EA

SERVICE LEVELS

How much could it cost?

Pricing depends on the amount and types of income, number of family members, companies and assets, number of scenarios modeled, and scope of implementation. Our objective is for the cost of planning to be economically justified by the potential result. Tax-return preparation, legal documents, technical studies, and outside professional services are billed separately unless expressly included in the proposal.
Black

Turn-key Implementation

$5,500
+ 20% of 1st year tax savings + tax returns and outside professionals
For business owners, investors, and high-tax families who want more than advice – they want a tax strategy that is designed and implemented for the year.
  • Tax strategy development
  • Hands-on implementation
  • Bi-weekly calls
  • Tax-preparer coordination
  • Documentation support
  • Tax audit support coordination
Schedule Consultation
Gold

Consulting Support

$3,500
+$500 quarterly + tax returns and outside professionals
For clients who need a quantified action plan and professional support in implementing the key decisions.
  • Tax strategy summary
  • Implementation plan
  • Quarterly advisory calls
  • Tax-preparer/accountant instructions
  • One-off documentation review
  • Initial tax audit support
Schedule Consultation
Silver

Diagnostic Review

$2,000
One-off
For clients who want to determine whether their situation contains sufficiently significant opportunities for full tax planning and which ones are worth modeling in detail.
  • Analysis of income, companies, and principal assets
  • Identification of the main sources of tax burden
  • Identification of 3-5 most relevant planning directions
  • Preliminary calculation of the most significant options
  • Priority actions before tax year-end
  • Final consultation and recommended next steps
Schedule Consultation

CASE EXAMPLES & TAX PLANNING NOTES

How Tax Planning Can Change the Activity Itself – Not Just the Tax Return

Examples are illustrative only. Tax results depend on the facts, the client’s level of participation, the economic substance of the activity, documentation, and the tax rules in effect.
A Business Owner Keeps the Former Home as an Investment While Preserving a Valuable Tax Exclusion
A family moves into a new home but wants to keep the former residence and use it as rental property. If the family simply continues to own the property for several years, the opportunity to use the Section 121 exclusion on gain from the sale of a principal residence may be lost. We model a sale of the property at fair market value to a related company, after which the property continues to operate as a separate rental asset. The transaction is structured in advance as a substantive commercial transaction, with an independent valuation, purchase agreement, financing, actual payments, separate accounting, and continued use of the property in a genuine rental activity.
Selling an asset does not always mean giving it up. Sometimes it is more advantageous to change the ownership structure in advance, preserving both the tax opportunity and the investment asset.
An Investor Turns Securities Trading Into a Separate Business
A client owns securities and expects significant gains from sales during the current year. We model a transition from investment activity to a bona fide securities-trading business together with a Section 475(f) mark-to-market election. If the requirements are met, gains and losses of the trading portfolio are treated as ordinary rather than capital, capital-loss limitations are removed, and wash-sale limitations do not apply to the covered trading positions; in some states, the income may also fall outside a separate state tax base on long-term capital gains. We design the transaction pattern, trading frequency, separation of investment and trading portfolios, and use of derivatives in advance as one economically justified trading strategy.
Properly structured activity can change not merely the amount of a deduction, but the tax regime applicable to the profit itself.

Blog/Video Insights

Latest Insights

U.S. Tax Planning for International Founders Moving to Florida

1 min read · Oleg Shmal · September 2026

Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. tax system.Relocating to Florida does not erase prior tax complexity. International founders need a coordinated plan for residency, business income, foreign accounts, and the transition into the U.S. […]

Keep Reading
Disclaimer
Tax planning depends on the client’s specific facts, the economic substance of the activity, the type and source of income, business form, level of participation, applicable federal rules and state law, timing, and actual implementation of the selected strategy. The examples above do not promise a particular result and may not apply in another situation.
Miami Tax & Tech does not guarantee any specific amount of tax savings, tax refund, or acceptance of a tax position by the Internal Revenue Service (IRS).